| Overview:
There is no universal minimum CIBIL score for a car loan, though most lenders prefer 750 and above for the best rates, while scores between 700–749 are often acceptable and 650–699 may require higher down payments or a co-applicant. Even with a score below 650 or no credit history at all, approval remains possible through NBFCs, stronger income proof, or adding a co-applicant, making it essential to check your score for free beforehand and take steps to improve it if needed. |
What Is the Minimum CIBIL Score Required for a Car Loan?
There is no single car loan eligibility criteria based on CIBIL score that every bank and NBFC follows. Most large lenders, however, prefer a score of 750 and above. Scores between 700 and 749 are often considered acceptable, while anything below 650 can make the process harder. The final decision rests on a mix of factors: your income, existing debt, down payment, and the lender’s internal risk policy. So while a benchmark exists, it is not a rigid cut‑off.
CIBIL Score Range for Car Loan Approval
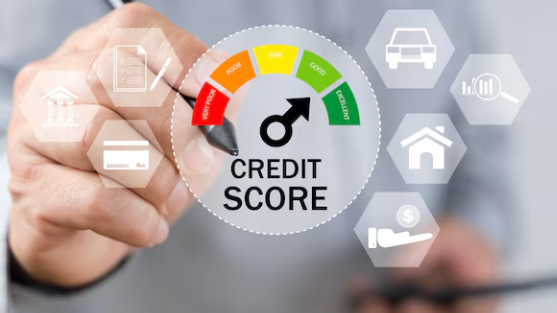
Lenders place every applicant into a rough CIBIL score range to decide whether to approve the loan; this is the credit score approval threshold that determines your fate. The table below summarises what each band typically means.
| CIBIL Score | Approval Chances | Typical Lender View |
| 750 and Above | High | Preferred borrower; likely to get competitive interest rates and faster processing. |
| 700 to 749 | Good | Approval probable, though the offered rate may be slightly higher than the best tier. |
| 650 to 699 | Moderate | May require a higher down payment or a co‑applicant; approval not guaranteed. |
| Below 650 | Low, but possible | Lenders assess income stability and repayment capacity more closely; terms will be stricter. |
750 and Above
A score in this band tells lenders you have managed credit responsibly. Most see it as a green light for a car loan.
700 to 749
Here you are still viewed as a reliable borrower, though the final interest rate might be a notch above the best offers.
650 to 699
Lenders often treat this as a borderline zone. They will weigh your income and employment stability more heavily before saying yes.
Below 650
Approval is not impossible. Some lenders, especially NBFCs, may still approve the loan if you can demonstrate strong cash flow or offer a substantial down payment.
Why Do Lenders Check Your CIBIL Score Before Approving a Car Loan?
Your CIBIL score for car loan applications acts as a quick summary of your credit behaviour, helping lenders assess your credit risk. It tells the lender how risky you are as a borrower before they even look at your income documents. A low score can flag past late payments or heavy existing debt, prompting the lender to either raise the interest rate or ask for a guarantor.
Repayment History
A clean record of on‑time EMIs and credit card payments is the strongest signal that you will service a car loan without trouble.
Existing Loan Obligations
If you already carry a large home loan or personal loan, the lender may worry that adding a car EMI will stretch your monthly budget too thin.
Credit Utilisation Ratio
Using a very high share of your credit card limits suggests you rely heavily on credit, which can push the lender to price the car loan more conservatively.
Recent Credit Enquiries
Applying for multiple loans or cards in a short span looks like credit‑hungry behaviour and can temporarily ding your score, making lenders cautious.
Can You Get a Car Loan with a Low CIBIL Score?
Yes, a car loan for low CIBIL score is possible, though the terms will not be as favourable. Lenders look for ways to offset the risk through repayment capacity evaluation, so you may need to bring extra strengths to the application:
- Apply with a co‑applicant who has a strong credit profile and stable income.
• Make a higher down payment to reduce the loan amount and the lender’s exposure.
• Show proof of steady, verifiable income through salary slips or IT returns.
• Choose a lower loan amount so the EMI burden stays well within your reach.
• Compare lenders, because NBFCs sometimes have more flexible car loan eligibility CIBIL score thresholds than traditional banks.
Taking these steps can shift the decision in your favour even when the score is not ideal.
Can You Get a Car Loan Without a CIBIL Score?
Yes, in some cases a car loan without CIBIL score is possible. First‑time borrowers and those who have never held a credit card or loan may have no credit history at all, shown as NH or NA on a credit report; so lenders rely on income stability verification instead. Lenders then assess alternative indicators: your income stability, the down payment you can bring, the loan amount requested, and whether you add a co‑applicant with a visible CIBIL score for car loan track record. A car loan minimum CIBIL score requirement does not apply when there is no score to check; instead, the focus shifts entirely to your capacity to repay.
How to Improve Your CIBIL Score Before Applying for a Car Loan
Raising your score before you submit a car loan application can unlock better interest rates and a smoother approval. Even a three‑ to six‑month effort often moves the needle enough to matter. Here are four practical steps that consistently improve CIBIL score health.
Step 1: Pay EMIs and credit card bills on time.
Every on‑time payment builds a positive trail, reinforcing consistent repayment behaviour that lenders value. Set up auto‑debit for at least the minimum amount so you never miss a date.
Step 2: Reduce your credit utilisation ratio.
Try to keep total credit card usage below 30% of the combined limit; a key practice in credit utilisation management. If necessary, make a mid‑cycle payment to bring the outstanding balance down.
Step 3: Avoid multiple loan applications.
Every hard enquiry may have a temporary impact on your score. Research lenders first, then apply to the one that best fits your profile.
Step 4: Review your credit report for errors.
Obtain your credit report and look for outdated accounts, incorrect personal details, or loans you did not take. If you find a mistake, use the Dispute CIBIL Errors process to get it corrected quickly.
Check Your CIBIL Score with Airtel Finance
Before approaching a bank for a car loan, see exactly where you stand. Airtel Finance lets you do a free CIBIL score check instantly and access a free credit report. With your score in hand, you can plan the right move, whether that means applying now or spending a few months strengthening your profile.
Conclusion
A CIBIL score for car loan eligibility is just one piece of the puzzle in car loan interest rate determination. Lenders also weigh your income, employment stability, and overall debt load. A score above 750 certainly opens more doors, but even a lower score does not shut them completely. By checking your CIBIL score for car loan readiness early and addressing any weak spots, you put yourself in the strongest possible position before signing on the dotted line. Check credit score for free on Airtel Finance today and take the first step toward a confident car loan application.
FAQs on Minimum CIBIL Score for a Car Loan
What is the minimum CIBIL score for a car loan?
There is no universal CIBIL score required for car loan approval. Most banks prefer 750 and above, but many NBFCs accept scores in the 650–700 range. The final call depends on your income, down payment, and overall car loan eligibility CIBIL score profile.
Can I get a car loan with a 650 CIBIL score?
Yes, a car loan for low CIBIL score with a 650 is often approved, especially if you present a stable job, a reasonable loan amount, and a co‑applicant with a stronger profile. Expect the interest rate to be higher than the best market rate.
Can I get a car loan without a CIBIL score?
Yes, a car loan without CIBIL score is available for first‑time credit users. Lenders then rely on your income proof, bank statements, and down payment amount. Adding a co‑applicant who has a credit score further improves your chances.
Does applying for a car loan reduce my CIBIL score?
A single car loan application triggers a hard enquiry, which can lower your score by a few points temporarily. However, if you apply to multiple lenders within a short window, credit bureaus often treat it as a single enquiry. The bigger risk is applying for several different credit products at once.
How can I improve my CIBIL score before applying for a car loan?
Pay all existing dues on time, keep credit card balances low, avoid applying for new credit unnecessarily, and dispute CIBIL errors on your report. These actions can push your score up over a few months and put you in a better CIBIL score range for car loan approval.
Does a co-applicant improve car loan approval chances?
Yes. A co‑applicant with a high CIBIL score for car loan eligibility and a stable income reduces the lender’s risk. This can lead to a higher loan amount approval when your individual score is borderline.