| Overview Your score sits at 500, and you may feel every financial door is shut, but it isn’t, as consistent steps can rebuild your profile over time. Knowing how to improve a 500 credit score starts with understanding the 500 credit score meaning and implications, adopting low credit score recovery strategies, and recognising the credit age importance for score improvement through oldest account preservation and anchor account establishment. |
Your score sits at 500, and you may feel every financial door is shut. It isn’t. Credit age makes up 15% of your CIBIL score, and you can start rebuilding today. Knowing how to improve a 500 credit score begins with understanding what that number really means and taking small, consistent steps.
What Does a 500 Credit Score Mean?
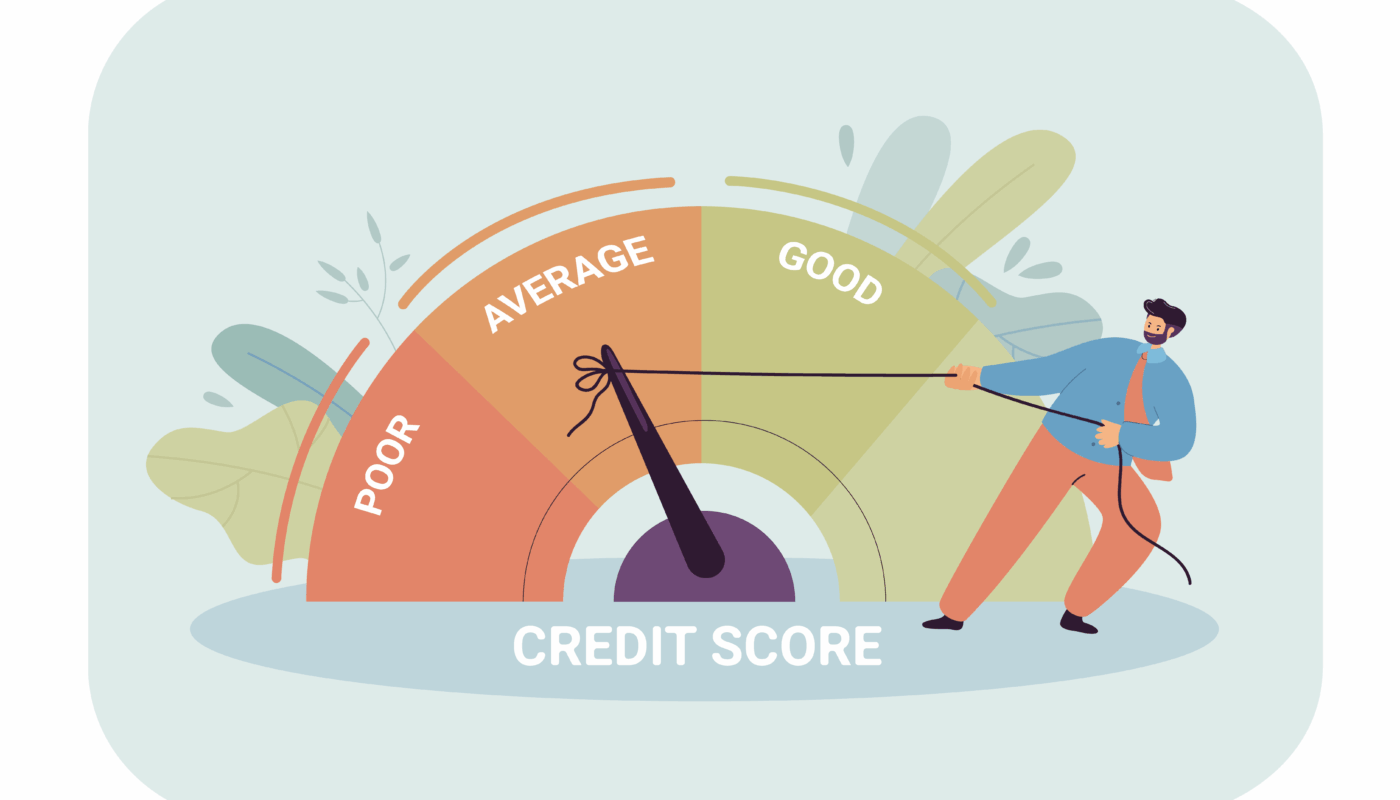
A 500 credit score signals to lenders that you are a high‑risk borrower. Most banks and NBFCs will hesitate to approve a loan or credit card at this level. It does not mean you are permanently locked out, but it does mean you will need to demonstrate steady, responsible behaviour over several months before you see meaningful improvement. Recognising this is the first move in any plan to improve a 500 credit score.
Why Does Your Credit Score Drop to 500?
A score can slide to 500 for a handful of reasons. Each one alone can do damage; combined, they push the number down quickly. Here are the most common triggers.
Missed or Late Payments
Even one missed EMI can dent your score. Multiple delays tell lenders you are unreliable with repayment.
High Credit Utilisation
Using more than 30% of your card limit signals credit hunger. Maxed‑out cards pull the score down fast.
Multiple Credit Applications
Every loan or card application triggers a hard enquiry, illustrating the hard enquiry impact on low scores. Several in a short span suggest credit desperation.
Loan Defaults
A settled or written‑off account stays on your report for years. It single‑handedly drags a score into the 500s.
How to Improve a 500 Credit Score
Rebuilding from 500 is not about shortcuts. It is about fixing the patterns that caused the drop, practising credit mix optimisation, and adding positive data month after month. Here are five practical actions to increase 500 credit score steadily.
Pay Bills and EMIs on Time
Set up auto‑pay for every loan and card. Even one 30‑day delay can stall your recovery.
Reduce Credit Utilisation
Keep card balances below 30% of the limit. Pay down high‑usage cards first to boost 500 credit score quickly.
Build a Longer Credit History
Open an anchor account like the Airtel Bajaj Finserv Insta EMI Card and let it age. Longer history lifts score weight.
Take a Secured Loan Responsibly
A gold loan (via Airtel Finance’s lending partner) adds a secured tradeline. Repay on time, and it strengthens your credit mix.
Monitor Your Credit Report Regularly
Pull your free credit report (worth ₹399) through Airtel Finance. Spot errors and track progress to raise 500 credit score reliably.
Why Credit Age Matters
CIBIL watches two things: the age of your oldest account, demonstrating oldest account preservation value and the average age of all accounts. A short history leaves the bureau with little to evaluate, keeping your score stuck in the 500s. Credit age only grows with time, you cannot rush it, but you can protect it from day one.
Keep Older Accounts Active
Do not close your first card or EMI account. A single old account can carry your entire credit age; close it and the score drops.
Build Long-Term Credit History
Start a fresh account now and never miss a payment. Every month adds positive data, slowly pushing the score upward.
Common Mistakes That Keep Your Credit Score Low
Even after you begin repairing your score, some everyday moves can undo the progress, undermining your responsible borrowing behaviour. Avoid these three pitfalls while you work to improve credit score from 500.
Closing Old Accounts Too Soon
Shutting your oldest card shrinks credit age and raises utilisation. Keep it open with a tiny quarterly purchase.
Missing EMI Payments
A single missed EMI stays on your report for years. During recovery, even one slip resets months of hard work.
Applying for Multiple Loans Together
Every application triggers a hard enquiry and lowers average age. If rejected, wait 3‑6 months before trying again.
How Long Does It Take to Improve a 500 Credit Score?
There is no overnight fix. With flawless on‑time payments and low utilisation, you may see a 30‑50 point rise in six months. Crossing 650 often takes 12‑18 months. The timeline depends on how many negative items your report contains. Patience and consistency are the real multipliers.
Conclusion
A 500 credit score is not a life sentence. It is a snapshot of past behaviour that can be rewritten with discipline. Start by paying on time, keeping balances low, and protecting old accounts. Check your free credit report regularly via Airtel Finance to monitor every gain. The journey to improve a 500 credit score begins with a single on‑time payment, make it today.
FAQs on Improving a 500 Credit Score
What Is the Fastest Way to Improve a 500 Credit Score?
The fastest route is to bring all past‑due accounts current, pay down credit card balances, and stop applying for new credit. Consistent on‑time payments from this point forward will start raising 500 credit score within months.
Can a Secured Loan Help Improve a 500 Credit Score?
Yes. A secured loan, such as a gold loan, adds a positive tradeline to your report. Because the loan is backed by collateral, approval is easier at a low score. On‑time repayments demonstrate creditworthiness and can boost 500 credit score incrementally.
How Often Should I Check My Credit Score While Improving It?
Check once a month. Airtel Finance gives you a free credit report worth ₹399. Regular monitoring helps you catch errors early and see exactly how your efforts translate into score changes. If you spot a mistake, file a CIBIL Dispute Online Guide to correct it.
Can a 500 Credit Score Affect Loan Approval?
Absolutely. Most lenders decline applications with a 500 score or offer only very small amounts at high rates. Even if you qualify, the terms will be unfavourable. Improving your score before applying significantly raises credit card eligibility and loan approval chances.
What Are the Biggest Mistakes That Keep a Credit Score Low?
Missing payments, maxing out credit cards, and frequently applying for new credit are the top three. Closing your oldest account also hurts. If you need help understanding your report, reach out to CIBIL Customer Care for official guidance. When you are ready to add positive history, you can apply for credit card options suited to your rebuilt score.