Check Your Credit Score for FREE
Know your CIBIL score instantly and understand your loan & card eligibility in seconds. ₹399 ₹0
✔ Verified Report
⏱ 2 Min Check
⚡ No Impact on Score
Get Flexi Credit up to ₹10 lakhs ✔️Instant disbursal ✔️100% online process
Check Now
Your Experian credit score is a quick snapshot of your credit health, and checking it shouldn’t cost a thing. Through Airtel Finance, you can view your Experian credit report, free of cost. You are also entitled, under RBI rules, to one free full credit report every calendar year from each of India’s four credit bureaus, including Experian. Your score moves as lenders report your borrowing and repayment activity, which now happens weekly. A free Experian credit check takes about two minutes and tells you where you stand and what lenders see when you apply for a loan or credit card. No hidden charges, and no impact on your score, because checking your own report counts as a soft enquiry.
If you're wondering what is Experian credit score, it is a three-digit number ranging from 300 to 900 that reflects your creditworthiness. Experian, one of India's four RBI-licensed credit bureaus, calculates it using data from your borrowing history. Lenders check this score to decide loan approvals, interest rates, and credit card eligibility. Essentially, Experian credit score meaning, a financial health indicator built from your past credit behaviour.
If you have never borrowed before, you may see NA or NH (no activity or no history) instead of a number. This is not a low score. It simply means Experian does not yet hold enough credit data to score you.
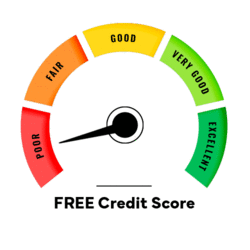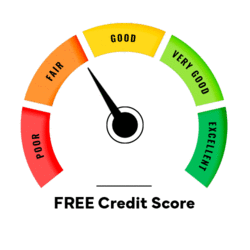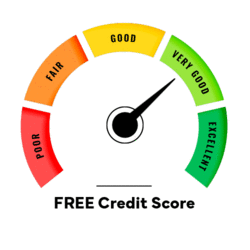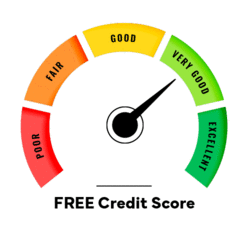
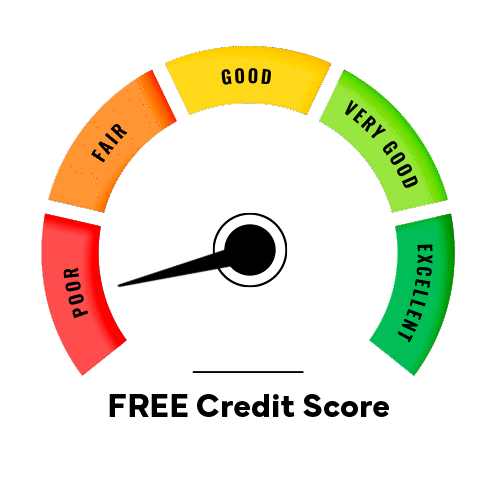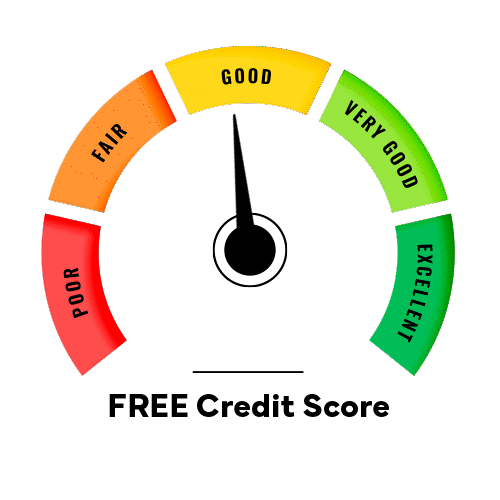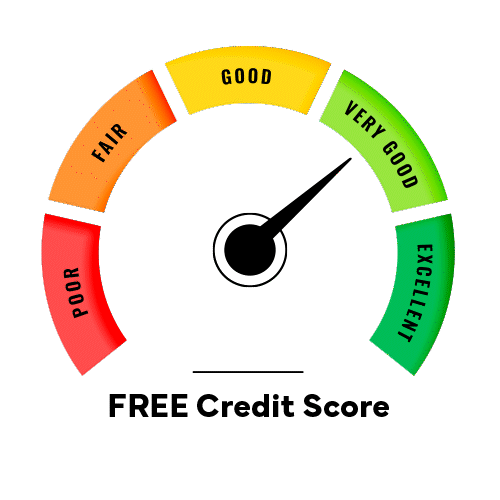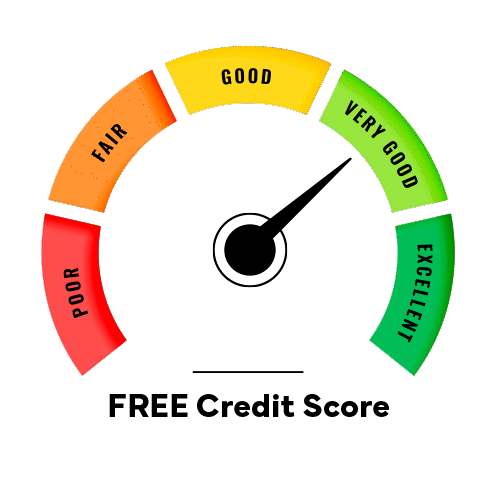
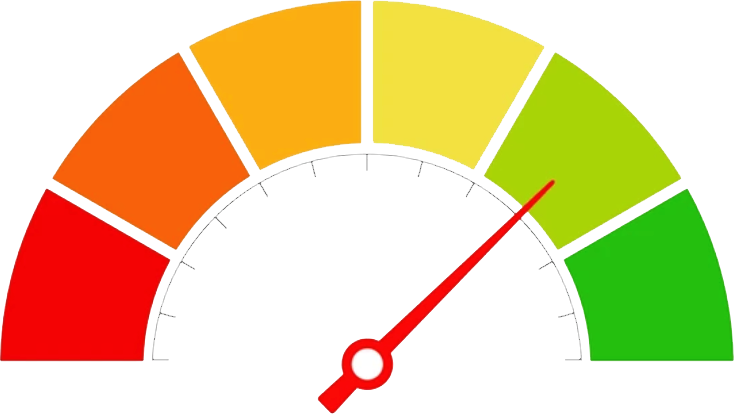
Experian credit score range from 300 to 900 and are typically interpreted as follows:
Loan approvals are hard to come by; if sanctioned, interest rates are high.
Most standard credit products become realistically accessible.
You're considered lower risk and tend to get better loan offers.
The best rates and credit terms are within reach.
These bands describe general interpretation, not a published Experian classification. Experian uses a proprietary scoring model and does not disclose exact weightings, and every lender applies its own cut-offs on top of the score.
In Indian lending practice, 700 and above is generally treated as good, and most lenders prefer 750 or above for standard retail lending. Once you cross 700, approval chances for loans and credit cards rise noticeably. A score above 750 opens doors to the most competitive interest rates, though final decisions still depend on your income, repayment capacity, and the lender's own policy.
Experian builds your score from several credit score calculation inputs: your repayment history, credit utilisation ratio, credit mix, length of credit history, and the number of new credit applications. Each factor carries a different weight. Experian India currently uses its V3 scoring model, and V3 scores can run roughly 50 points lower than scores generated under the older V2 model, so a change in your number does not always mean a change in your behaviour. No single late payment defines your score; it's the pattern over time that matters most.
Airtel Finance makes an Experian credit score check quick and completely digital. You don't need to visit a branch or submit physical documents. You will need to share basic KYC details, including your PAN, so that the bureau can match your record accurately and securely. The whole process takes about two minutes.
Open the Airtel App, go to the Airtel Finance section, and tap ‘Credit Score’. Enter your full name, date of birth, PAN, and registered mobile number. This step ensures the report you see belongs to you and no one else.
After submitting your details, the app may ask for an OTP sent to your mobile number. This two‑step check confirms your identity and protects access to your credit report. Once verified, the system pulls your latest Experian data.
Your Experian credit score appears on screen within moments. No paperwork, no waiting for a call-back. You’ll see the three‑digit number along with a brief summary of your credit standing.
Beyond the score, you get your full Experian credit report. It lists your personal and identity details, employment information, active and closed loans, credit cards, your repayment track record, and any recent enquiries. Scroll through to spot anything unusual, such as an incorrect outstanding balance, a loan you have already closed, or an account you don't recognise. To get a complete view of your credit profile, you can also check your CRIF Credit Report and compare information across credit bureaus.
Lenders and credit bureaus look at several moving parts. Understanding these elements helps you take control of your online credit score check and overall profile.
Paying bill payments and EMI payments on time is the single most influential factor. Every missed or delayed payment drags your score down, and the damage can linger for months.
The credit utilisation ratio compares how much credit you’re using to your total limit. Keeping it under 30% signals that you aren’t overly dependent on credit, which works in your favour.
A healthy credit mix, such as a home loan, a credit card, and perhaps a personal loan, shows you can handle different types of debt responsibly. It adds variety to your credit profile without complicating it.
Older credit accounts anchor your score. A long, clean history tells lenders you’ve managed obligations over years. Closing your oldest card removes an active account from your profile and can weaken this factor over time, even though closed accounts continue to appear on your report for several years.
Each new credit application triggers a hard inquiry. Several applications in a short span can hint at credit hunger, which often leads to a dip. Enquiries remain visible on your report for a few years, though their effect on your score fades well before that. Space out applications unless there's a genuine need.
Small, consistent steps move the needle faster than you’d think. Focus on the basics.
Automate your bill payments and EMI payments wherever possible. Even one 30‑day delinquency can dent your Experian score, so set reminders or enable auto‑debit.
Use no more than 30% of your total credit limit. If your limit is ₹2 lakh, aim to keep outstanding balances under ₹60,000. That low credit utilisation ratio tells lenders you’re in control.
Apply for new credit only when you really need it. Multiple applications in quick succession create unnecessary hard inquiries, which can shave points off your Experian credit score for up to a year. The effect usually fades over the following months, even though the enquiry itself stays on your report for longer.
Hold on to your older credit accounts, since they anchor your length of credit history. If you spot an error in your Experian report, raise a dispute resolution request with the bureau right away. Clean, long-standing accounts boost reliability in the eyes of lenders.
Ready to see your number? Airtel Finance lets you do an Experian credit score free check in seconds. Download the Airtel App, head to the Finance tab, and tap ‘Credit Score’. You can also access your Experian free credit report through the Airtel App at no additional cost. Stay informed, catch errors early, and plan your next loan or credit card move with confidence.




It will take 2 mins and is absolutely free. We promise!
Check your Free Credit ReportKnow your CIBIL score instantly and understand your loan & card eligibility in seconds. ₹399 ₹0