Check Your Credit Score for FREE
Know your CIBIL score instantly and understand your loan & card eligibility in seconds. ₹399 ₹0
✔ Verified Report
⏱ 2 Min Check
⚡ No Impact on Score
Get Flexi Credit up to ₹10 lakhs ✔️Instant disbursal ✔️100% online process
Check Now
Your CIBIL report download shapes every loan and credit card decision. Airtel Finance gives you a free credit report worth ₹500, CIBIL and CRIF certified, in minutes — no hidden fees, no complicated forms. It is a simple way to understand your credit standing and spot problems before a lender does.
You can get your CIBIL report through two trusted routes — directly from the CIBIL website or through Airtel Finance. The official CIBIL website allows you to access your credit information through its verification process, while Airtel Finance provides a free CIBIL and CRIF credit report on the Airtel App. These reports help you review your credit history from recognised credit bureaus.
Airtel Finance provides a zero‑cost, instant credit report on the Airtel App — CIBIL & CRIF certified, worth ₹500.
The official CIBIL website provides one free CIBIL score and report per calendar year, as mandated by the RBI, after PAN‑based identity verification and OTP authentication. Additional reports within the same year require a paid subscription.
Follow these steps for a free CIBIL report download through Airtel Finance with no payment, and no subscription:
Open the Airtel App on your phone and sign in with your mobile number.
Tap ‘Finance’ in the bottom menu, then select “Check Credit Score.”
Enter your details — full name, PAN, date of birth, and email ID.
Complete OTP verification, submit to fetch your report instantly, and view or share your complete CIBIL report right inside the app.
Your CIBIL report download pdf is essential for record‑keeping, loan applications, or sharing with a financial advisor. The PDF contains your entire credit history in a single file, password‑protected for safety.
After viewing your report on the app, use the download or share icon to save it as a PDF file.
Use the password format shown on screen or in the accompanying email at the time of download. Bureau-issued reports commonly use either the first four letters of your name as per PAN in lowercase followed by your birth year, or your date of birth in DDMMYYYY.
Only download on a secure, private network; never store the PDF on a shared device, and delete temporary files afterwards.
Your CIBIL report is a detailed summary of your borrowing behaviour. Lenders examine every section, so knowing what appears helps you stay credit‑ready.
Name, date of birth, PAN, [Aadhaar Redacted], current and previous addresses, and employer details as reported by lenders.
All active and closed loan accounts, credit cards, overdrafts, and their sanctioned amounts, current balances, and account status.
Month‑on‑month record of payments. It shows on‑time payments, late payments (30/60/90 DPD), defaults, and settled or written‑off accounts.
Every credit enquiry made by a lender when you apply for a loan or credit card. Too many such enquiries in a short span can temporarily lower your score. Checking your own report is a soft enquiry and does not affect your score.
Lenders don’t just look at the three‑digit number. They scan several sections to judge credit card eligibility and loan repayment capacity. Besides your CIBIL report, reviewing your Equifax Credit Score can provide another perspective on your overall credit profile.
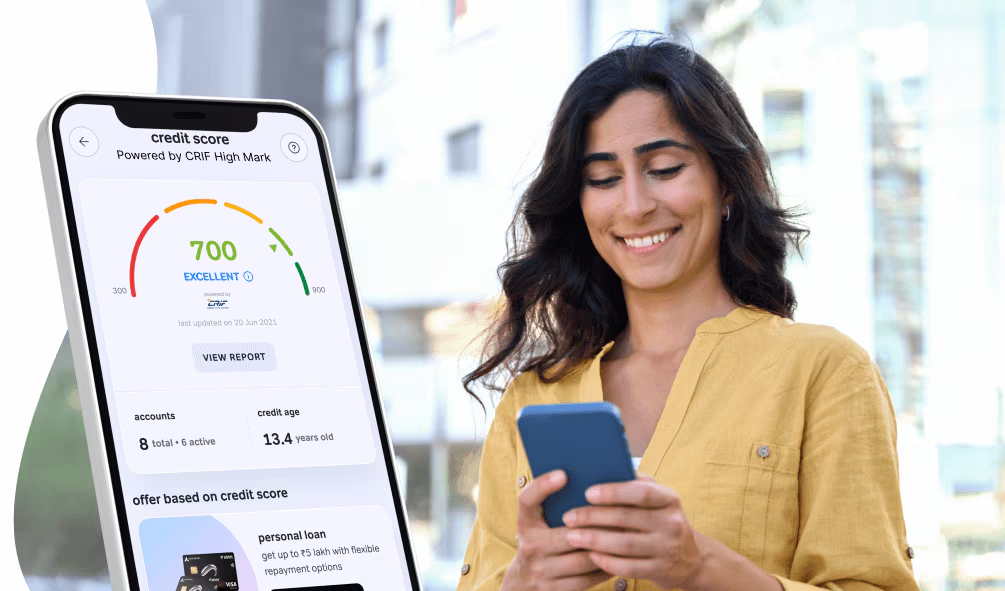
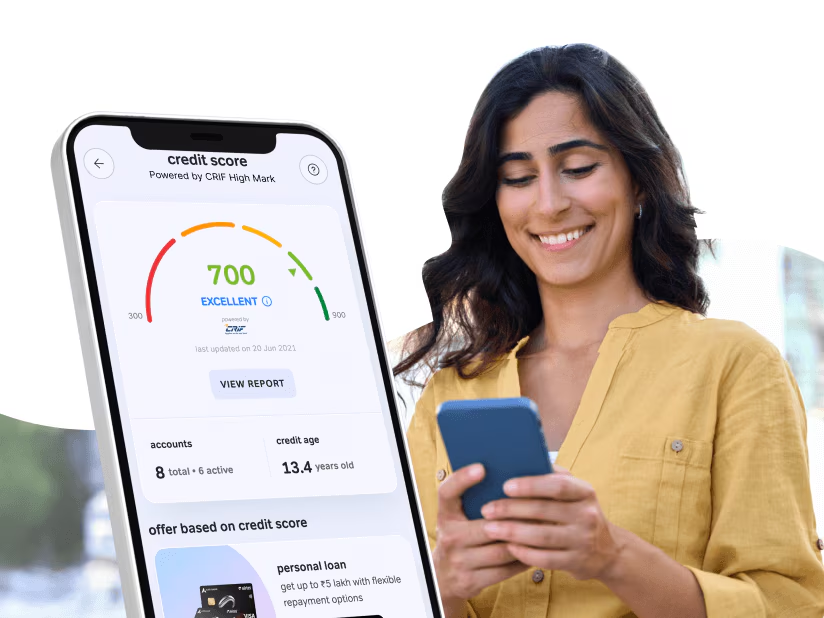
A score of 300‑900, where above 750 is considered excellent by most lenders and improves your credit card eligibility significantly. If you have not had an active loan or credit card in the last 36 months, you may see NA or NH instead of a score.
Shows if you have paid EMIs and card dues on time. Even a single 30‑day delinquency can drag your score down.
The percentage of your credit limit in use. Keep it below 30% across all cards to signal responsible credit behaviour.
Number of open loans, the mix of secured (home, car) and unsecured (personal, credit card) credit, and the age of your oldest account.
A few technical or data‑mismatch hurdles can interrupt your CIBIL report download. Most are easy to fix on the spot.
Your number must be the one linked with your bank/credit accounts. If you do not receive the OTP, check if the number is registered with the bureau.
Enter your PAN and date of birth exactly as on your PAN card. Even a single-digit mismatch can fail the identity check.
If the PDF does not save, update the app, clear cache, or use a different browser if on the CIBIL website.
Address or employer data may be outdated. Update your records with your bank and raise a dispute with the bureau, which must be resolved within 30 days. Re-fetch the report after about 30 days to confirm the correction.
A one‑time check isn’t enough. Routine monitoring protects your credit health and helps you stay ahead of any unpleasant surprises.
Track score movements. A gradual rise reflects good repayment behaviour, while a sudden dip needs investigation.
Clerical mistakes (wrong account, duplicate loan, incorrect outstanding) can hurt your score. Spotting them early lets you raise a dispute.
A clean report with a strong score puts you in the best bracket for lower interest rates and faster approvals.
A loan or card you never applied for might show up. Early detection stops fraud from damaging your credit history.




It will take 2 mins and is absolutely free. We promise!
Check your Free Credit ReportKnow your CIBIL score instantly and understand your loan & card eligibility in seconds. ₹399 ₹0